Picture two landlords selling identical duplexes on the same block, for the same price, in the same month. One writes the IRS a modest check. The other owes several times as much, all because of depreciation he claimed for years and then forgot about. Same building and same sale price, yet the tax bills look nothing alike.
Why Your Cost Basis Decides the Tax Bill
Get your cost basis wrong and you’ll pay capital gains tax on money you never made. It happens all the time, because people grab the purchase price from the closing statement and stop there.
Your basis starts with what you paid for the property. Then you add capital improvements, like a new roof, a new HVAC system, fresh wiring, or an addition off the back. Some closing costs from when you bought it count too. Repairs are a different animal, since fixing a leaky faucet doesn’t count the way a new furnace does, and that line trips up plenty of owners.
Last, you subtract the depreciation you claimed while it was a rental.
So dig out old invoices, contractor emails, and whatever you logged in QuickBooks. Say you can prove $60,000 of improvements over two decades. You’ll owe tax on a much smaller gain than the seller who shrugs and says the receipts are long gone.
Which Adjustments Change That Number
These adjustments pull in both directions, which a back-of-the-envelope estimate usually misses. Improvements raise your basis, while depreciation drags it back down. Selling expenses, such as agent fees and title charges, cut your net proceeds and shrink the gain.
Inherited property and rental property each play by their own rules. Both get a section below.
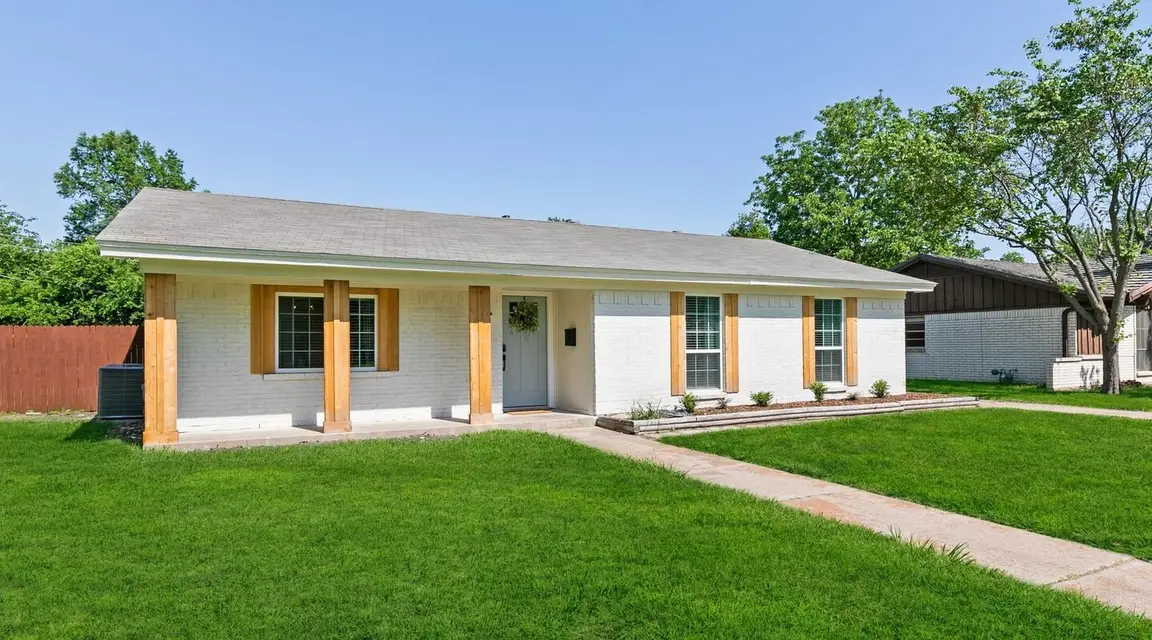
Not long ago I bought a brick ranch from three siblings who’d inherited it and spent two years splitting a rent check three ways. None of them wanted to be landlords. On a Tuesday walkthrough, the youngest brother told me he just wanted it done before another tenant called about the water heater.
What the 2026 Market Means for Your Timing
According to the National Association of Realtors, the median existing-home price hit $429,100 in August 2026. That’s up 1.6 percent from a year earlier. Supply reached 4.9 months that same month, the highest level in over a decade.
Buyers have room to negotiate again. Sellers can’t just name a number and wait.
Homes that did sell still moved at a decent clip, with a median of 29 days on market in May 2026, though that figure covers houses in listing shape. A tired property with a tenant still inside rarely keeps that pace, and I’ve seen it firsthand when buying occupied rentals.
Rising prices grow your gain, and the capital gains tax waiting at closing grows with it. If you’re weighing whether to list or sell directly, the team at Ready House Buyer can price it as-is, tenant and all, and give you a real number to compare.
How Does Capital Gains Tax Work on a Home Sale?
Selling a property you’ve held for just under a year is a costly mistake.
Own an asset for a year or less and the profit counts as a short-term gain, taxed like ordinary income at rates from 10 to 37 percent. Hold it longer than one year and the long-term capital gains tax rates kick in instead, and they’re far gentler. I’ve watched sellers save real money just by pushing a closing back a few weeks.
For 2026, the IRS set the 0 percent bracket at taxable income up to $49,450 for single filers. Married couples filing jointly get up to $98,900. Above those lines the rate steps up to 15 percent, and it climbs to 20 percent once taxable income passes $545,500 single or $613,700 joint.
Your gain stacks on top of your other income for the year, so a big sale can push you into a higher band than you’d normally land in. You’ll report it on Schedule D, the form for capital gains and losses, along with Form 8949.
How Do You Calculate Your Capital Gain?
A retired couple once called me sure they owed nothing, since they’d bought their rental in the nineties for a fraction of today’s value. What they’d forgotten was fifteen years of depreciation deductions sitting on their old returns.
The formula is plain math. Start with your sale price, subtract your selling costs, then subtract your adjusted cost basis, and the number that’s left is your capital gain.
Say you bought for $180,000, added $45,000 in improvements, and claimed $70,000 of depreciation. Your adjusted basis lands at $155,000. Sell for $340,000 with $25,000 in closing costs and commissions, and your gain comes to $160,000.
That whole amount won’t be taxed at one rate. The slice tied to depreciation gets treated separately, as the recapture section below explains. Software like TurboTax from Intuit can walk you through the split. In every sale I’ve worked on, though, sloppy records in meant sloppy numbers out.
What Is Step-up Basis on an Inherited Home?
For years I assumed heirs took over the original owner’s basis, tax headache and all. In most cases they don’t.
Under Section 1014, inherited property generally resets to its fair market value on the date the previous owner died. Decades of rising value drop out of the picture for income tax purposes. The depreciation the deceased claimed washes out with it.
That’s why an heir who sells soon after a death often owes little or no capital gains tax.
Families lose money when they never get a date-of-death value on paper. Five years later the house sells, and nobody can show what it was worth when Dad passed. Order the appraisal during probate, even if you aren’t sure you’ll sell, because its fee is small next to what a solid basis figure can save.
Has your family ever pinned down that value?
How Does Depreciation Recapture Affect Rental Property Sales?
A landlord I worked with had penciled out her tax and planned a trip with what was left. Her CPA came back with a number nearly double her estimate, and the trip got shorter.
Depreciation recapture was the reason. Each year you deducted depreciation on a rental, you lowered your taxable rental income. The IRS takes some of that benefit back when you sell.
For residential rental buildings, the part of your gain that matches the straight-line depreciation you claimed is called unrecaptured Section 1250 gain. It’s taxed at your ordinary rate, capped at 25 percent, and only the gain above that layer gets the friendlier long-term rates.
On top of that sits the Net Investment Income Tax of 3.8 percent. It applies once your modified adjusted gross income tops $200,000 single or $250,000 joint. Most states tax the gain as well, though Tennessee has no broad personal income tax.
Owners who skipped the deduction get hit hardest. Recapture covers the depreciation you were allowed to take, whether you claimed it or not.
Do You Qualify for a Hardship Exemption?
Maybe the place was your home first. If so, this section could save you a lot.
The Section 121 exclusion lets you shield up to $250,000 of gain, or $500,000 filing jointly. You must have owned the home and lived in it as your main home for at least two of the five years before the sale. IRS Topic 701 covers both tests, and the two years don’t need to come in a row.
Fall short of two years and you may still get a partial exclusion. The IRS doesn’t use the phrase hardship exemption, though the partial exclusion works much like one. It applies when you moved for a new job, for health reasons, or because of certain events you couldn’t see coming. TurboTax from Intuit explains how the prorated math runs.
The exclusion never covers depreciation taken after May 6, 1997. That layer still gets taxed. Rental years before you moved back in can also shrink the excluded amount. Ask a CPA before you count on the full figure.
A woman in Chattanooga, Tennessee reached out to me while settling her father’s estate. Her employer was moving her, she had five weeks to get out, and her dad’s fishing boat still sat under the carport. She skipped the listing and closed before her transfer date.
Frequently Asked Questions
What Are the Federal Capital Gains Rates for 2026?
Long-term gains still fall into three tiers, from zero up to a middle rate and a top rate. The income cutoffs moved up a bit for inflation this year, and the exact figures sit in the section on how capital gains tax works. Short-term gains on anything held a year or less get taxed as regular income, which is almost always worse.
How Is a Rental Property Taxed When I Sell It?
Your profit splits into two buckets. The slice matching the depreciation you claimed gets its own capped rate. Everything above that gets long-term capital gains tax treatment. State tax and the investment income surtax may stack on top, depending on your state and income.
Is There a Simple Trick for Avoiding Capital Gains Tax?
There’s no trick, though there are legal tools. A 1031 exchange defers the tax when you roll the proceeds into another investment property. You get 45 days to identify the replacement and 180 days to close, or less if your tax return comes due sooner. Moving into the rental and meeting the residence test above can also shelter some gain. Talk to a CPA before you sign anything.
What Is the 50% Rule for Rentals?
It’s an investing rule of thumb, not a tax rule. It assumes about half your rent will go to operating costs over time, like repairs, vacancy, insurance, property taxes, and management. Whatever’s left covers the mortgage. Investors use it to sanity-check a rental in about thirty seconds, and it has nothing to do with what you owe the IRS at closing.
Does Selling a House Count as Income?
Not the way a paycheck does. Only the gain can be taxed, and only what’s left after your exclusion and your adjusted basis. Plenty of sellers walk away owing nothing. You’ll likely still get a 1099-S from the closing agent, so the sale gets reported either way.
Can I Deduct Closing Costs and Repairs From the Gain?
Selling costs like agent commissions, title fees, and transfer taxes reduce your gain. Capital improvements get added to your basis, whether that’s a new roof, an added bathroom, or a replaced HVAC system. Routine repairs and cosmetic touch-ups generally don’t. Keep receipts, even old ones.
The Short Version
Figure out your basis, subtract it from the sale price, and see what’s really left. Hold past the one-year mark if you can. Check whether the residence exclusion covers you. If it’s a rental, account for depreciation recapture before you spend the proceeds in your head.
Then run the numbers with a CPA who sees your whole picture. Treat everything here as a map rather than a tax opinion.
If you’d rather skip the listing, the showings, and the repair talks, we buy houses across Tennessee in as-is condition. We can make you a cash offer to compare. There’s no pressure and no fee, and no hard feelings if the traditional route suits you better. Reach out whenever you’re ready and we’ll talk it through.